FirstQFM Quantum Forecasting System Outperforms Classical Benchmarks in Pilot Study
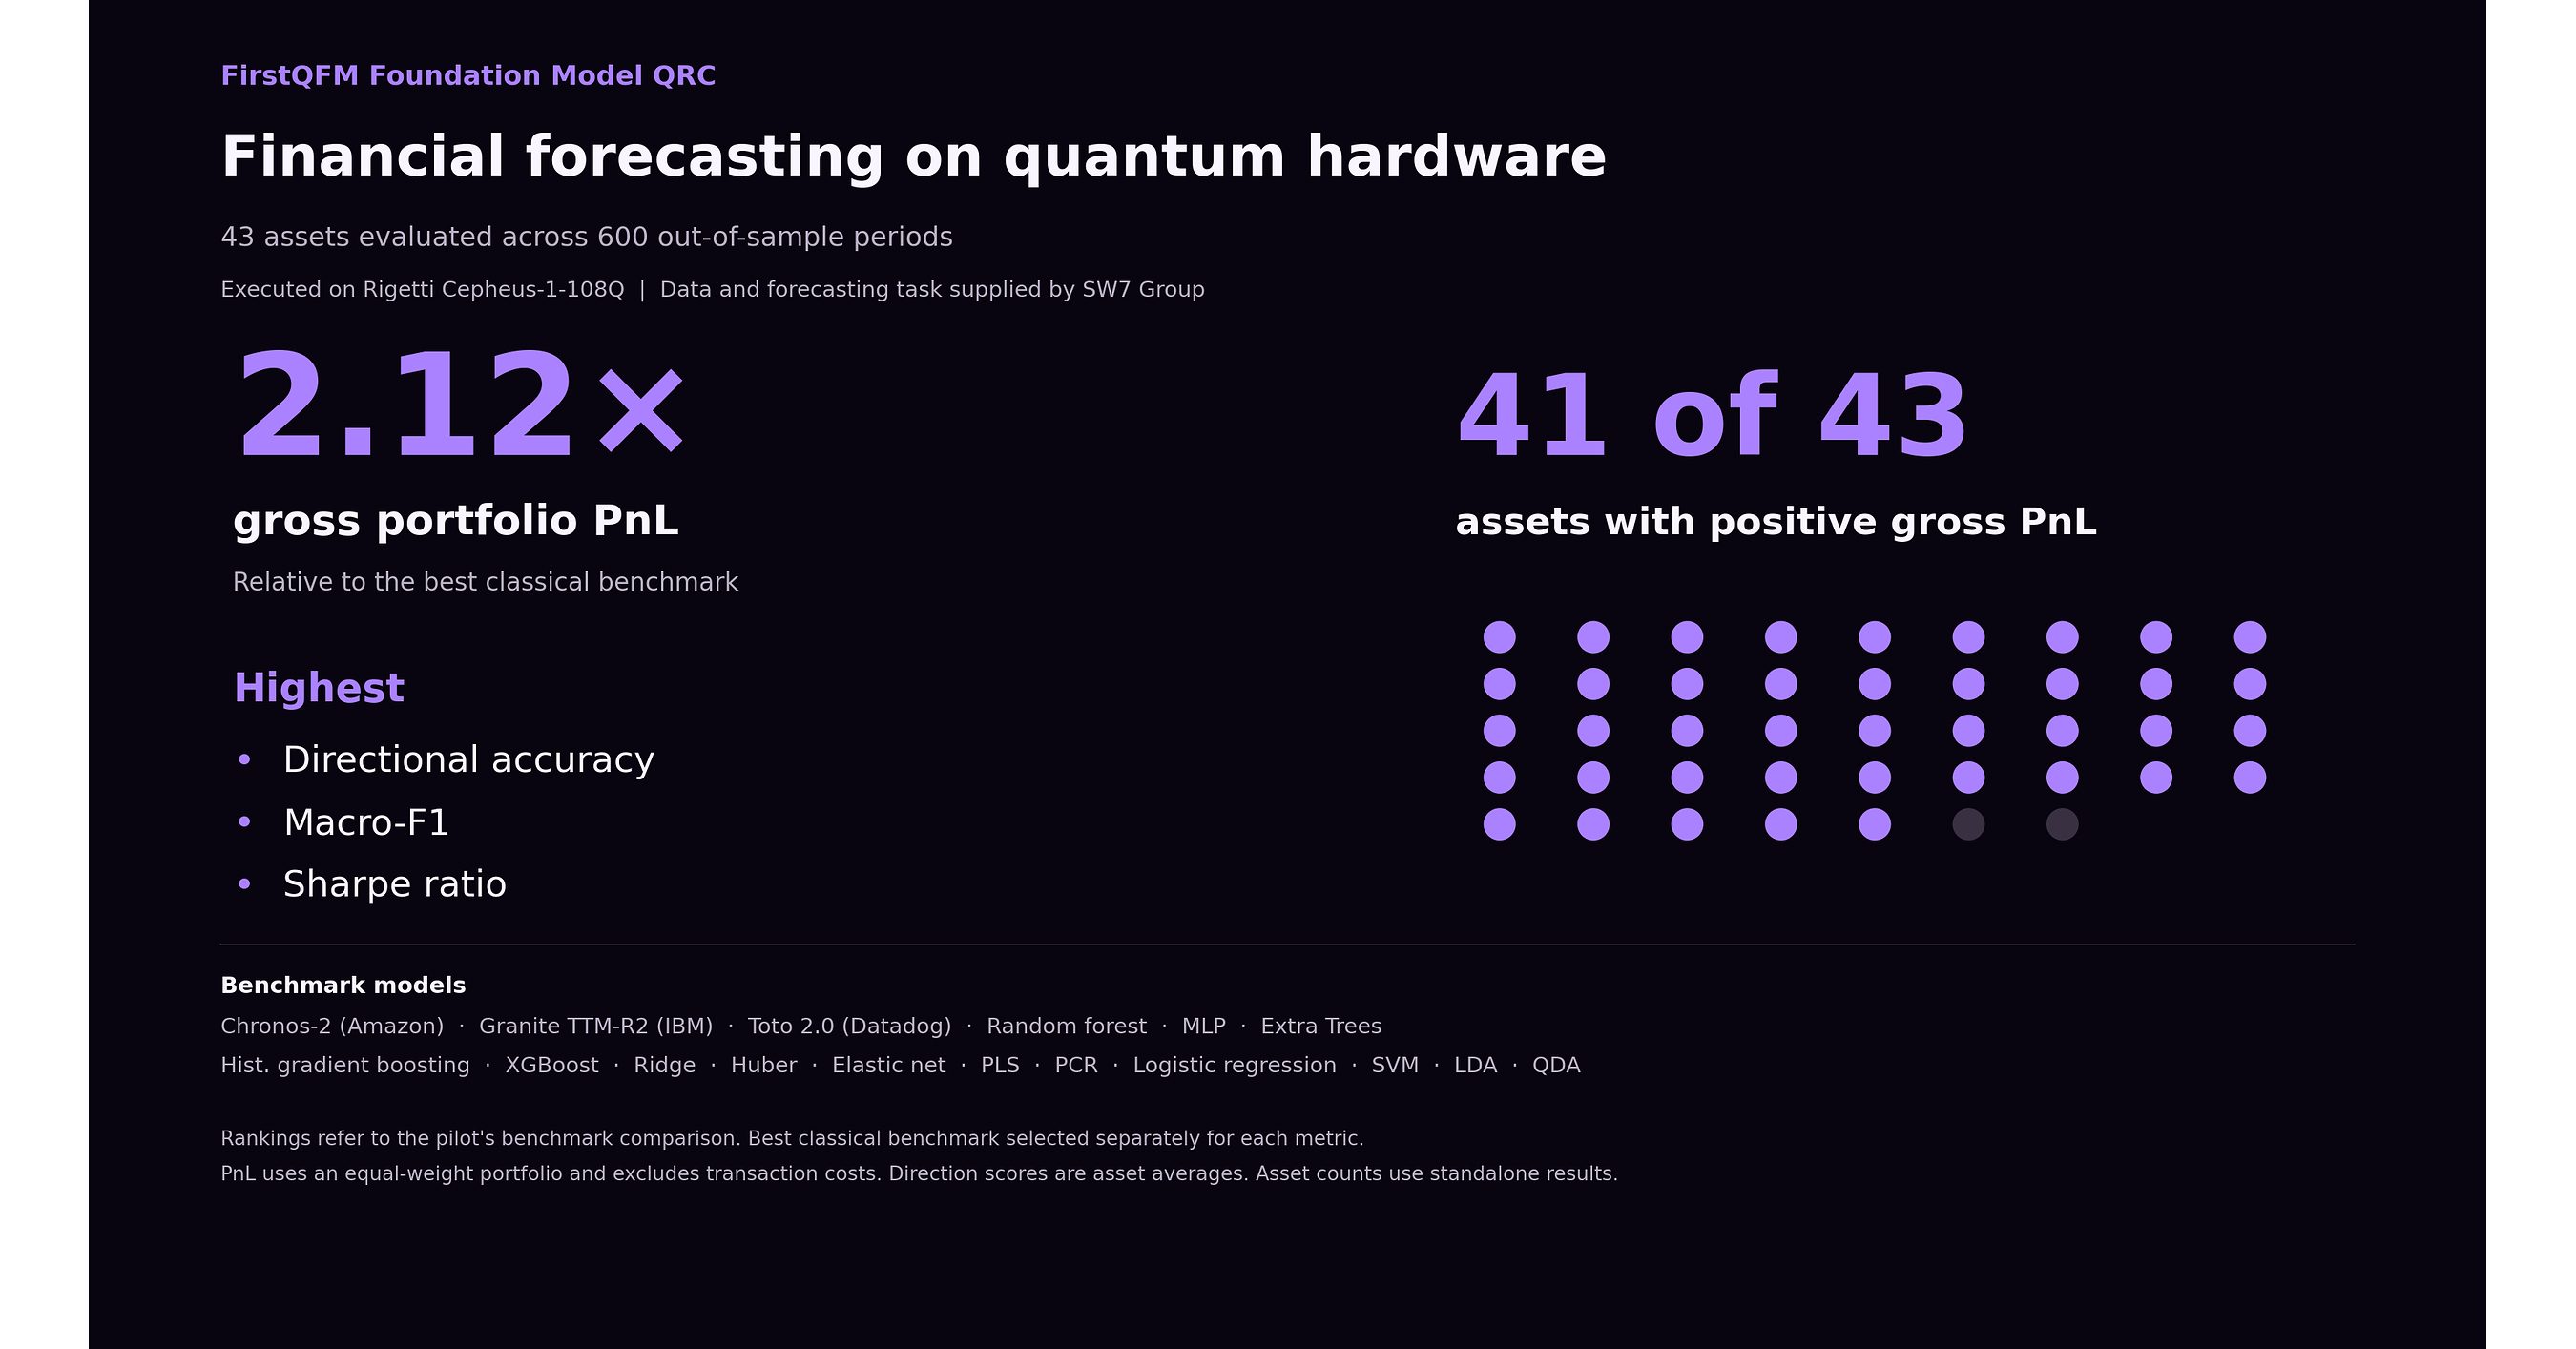
FirstQFM has announced successful results from a pilot program using its proprietary foundation-model-based quantum reservoir computing (QRC) system. Running on Rigetti Computing's Cepheus™-1-108Q hardware and utilizing data from SW7 Group, the system outperformed leading classical benchmarks in financial forecasting tasks across 43 anonymized assets. The evaluation demonstrated superior performance in key metrics, including a 52.02% directional accuracy and an annualized Sharpe ratio of 1.22 for an equally weighted portfolio. This represents a significant improvement over state-of-the-art classical models such as Amazon's Chronos-2 and IBM's Granite TTM-R2. A specialized five-asset portfolio further demonstrated high efficiency with a Sharpe ratio of 1.73. This milestone highlights the growing potential for quantum machine learning (QML) to provide practical value in quantitative finance, moving closer toward utility-scale applications in asset management and banking.
Tickers: $AMZN $DDOG $IBM $RGTI
Topics: algorithmic trading financial forecasting machine learning quantum computing